BUSINESS
Raising the Social Security Wage Cap Still Leaves a Hole
Republicans will entertain a higher Social Security tax cap, but lifting it covers about half the long-term hole and breaks the benefit bargain.

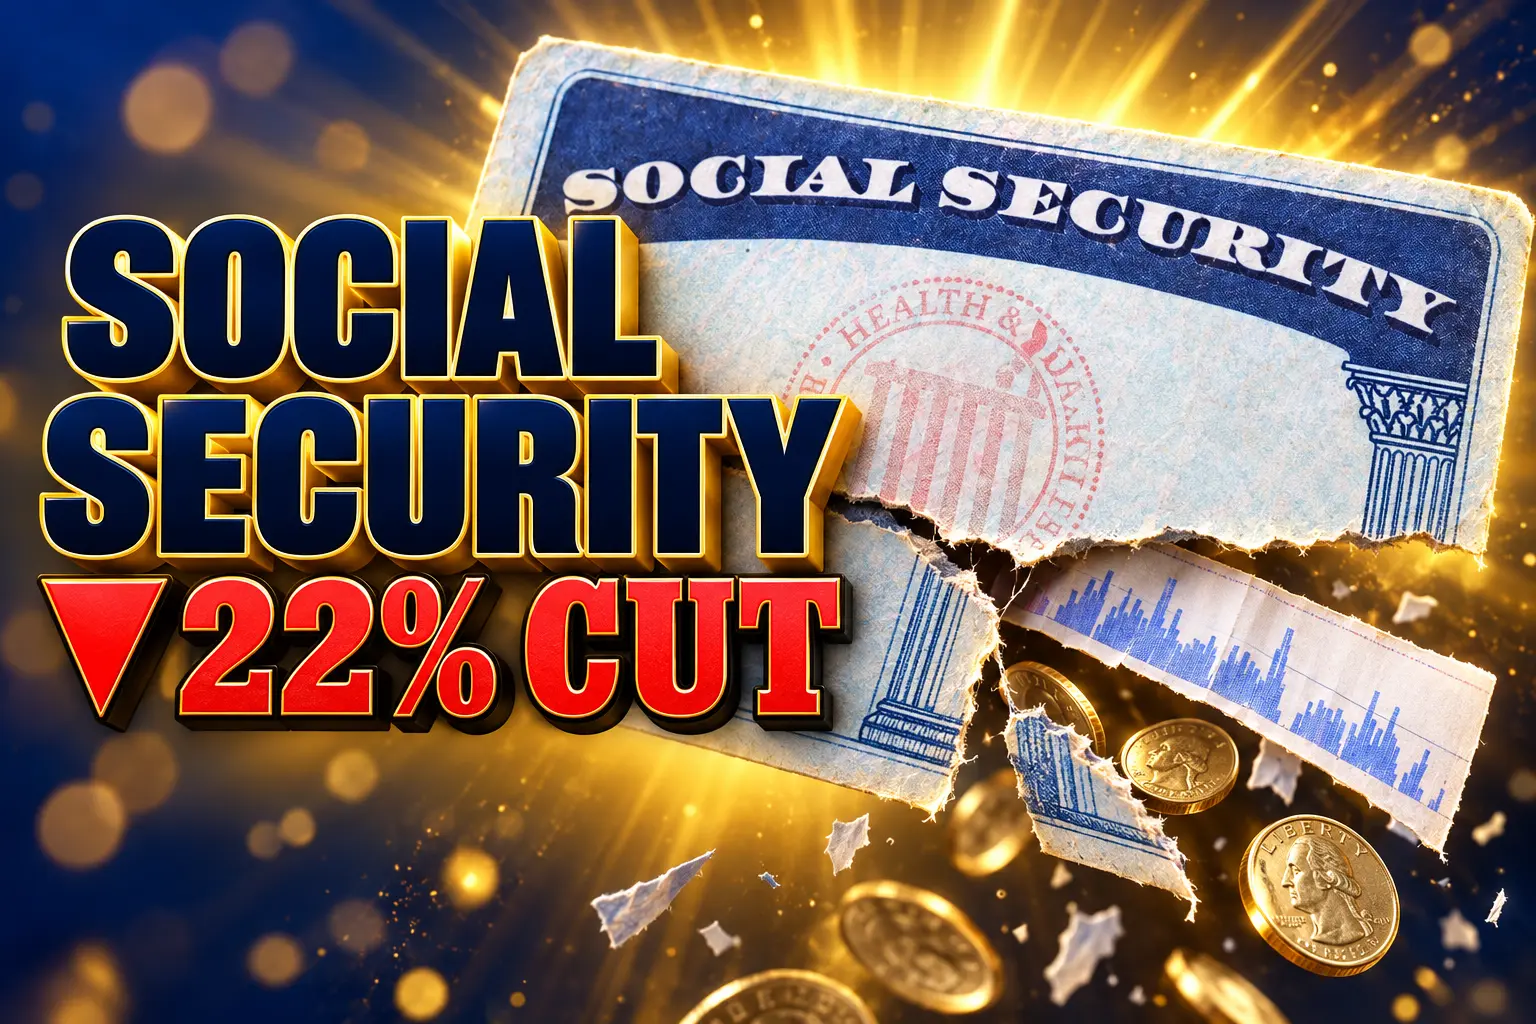
House Republicans who spent careers treating tax hikes as poison have begun talking about a higher Social Security tax cap, with the retirement trust fund due to empty in late 2032. The program’s trustees say incoming taxes would then pay 78 percent of scheduled benefits, an automatic 22% cut in every check.
Scrapping the $184,500 ceiling would still leave a large share of the 75-year hole unfilled. Taxing extra wages without raising extra benefits would also break the old link between what a worker pays and what that worker later collects.
The Trust Fund Hits Empty in Late 2032
The 2026 Trustees Report, released June 9, moved the Old-Age and Survivors Insurance fund up by one quarter, to the fourth quarter of 2032. Disability Insurance is separately projected to last through 2100, so the two funds together would last until the third quarter of 2034, and only if Congress first changed the law to combine them. At that combined date, 83 percent of scheduled benefits would be payable, a 17 percent cut.
THE 2032 CUT IN PLAIN NUMBERS
- OASI depletion: Full checks until late 2032, then 78 percent of scheduled benefits, falling to 62 percent by 2100, a 38 percent cut.
- 75-year gap: A combined OASDI deficit of 4.42% of taxable payroll, up from 3.82 percent in the prior report, which the Committee for a Responsible Federal Budget calls 16 percent larger.
- Present value: That shortfall equals $31 trillion on a present value basis, CRFB said, with cash deficits of $3.8 trillion over the next 10 years.
- If Congress waits: An immediate repair would take a 4.25 point payroll-tax rise, a 34 percent jump, or a 25 percent benefit cut. By 2034 those figures become 4.9 points, a 40 percent tax rise, or a 29 percent cut.
Program costs already run at 15.2 percent of payroll against revenues near 13.1 percent. CRFB projects costs at 16.9 percent of payroll by 2050 and 20.0 percent by 2100, with revenues only inching to 13.5 percent. A typical couple retiring in 2033 would lose about $18,400 a year if the automatic cut hit, CRFB has estimated.
Three changes did most of the damage in this year’s book. The trustees cut the long-run fertility rate from 1.90 children per woman to 1.75, lowered immigration, and scored the One Big Beautiful Bill Act, signed July 4, 2025. That law locked in lower income-tax rates, a larger standard deduction, and a temporary extra deduction for people over 65, which reduces the income tax collected on Social Security benefits. CRFB put the tax law’s hit at 0.16 percent of payroll.
I’m willing to look at the tax rate. I am willing to raise the amount of income through tax.
Rep. Tom Cole, R-Okla., House Appropriations chairman
Cole, speaking in early September, added that the country would have a much bigger problem if the program went bankrupt than if lawmakers kept it whole, “because people will feel cheated.” Rep. Lloyd K. Smucker, R-Pa., a leading candidate to run the House Budget Committee, told reporters that lawmakers would probably have to do something on the payroll half of the money paid into the system, and that they cannot allow a benefit cut in six years.
The Wage Cap Now Misses a Growing Slice of Pay
Workers and employers each pay 6.2 percent, 12.4 percent combined, on wages up to the maximum taxable earnings of $184,500 in 2026. Self-employed people pay the full 12.4 percent. Once a paycheck crosses that line, the Social Security tax stops. Medicare’s hospital tax does not: that 1.45 percent levy, plus a 0.9 percent extra tax on high earners, has no annual ceiling.
At the 2026 cap, the most an employee owes is $11,439, and the most a self-employed person owes is $22,878. A nurse whose wages sit under the cap pays 6.2 percent all year. An executive at $1 million pays the same $11,439 and then zero Social Security tax on the rest. Tyler Bond, a senior fellow at the National Academy of Social Insurance, says about 6 percent of workers clear the cap in a given year, and only about 20 percent ever do so in a career.
That ceiling is not an accident of fairness. It is the other side of the benefit formula. Social Security counts only wages up to the cap when it sets a later check, so a $250,000 salary and a $1 million salary produce the same earnings credit once both pass $184,500. The political fight over “making the rich pay” is, in practice, a fight over whether to tax pay the program will not count.
When Congress last rebuilt the system, it did not reach for the cap alone. President Ronald Reagan signed the Social Security Amendments of 1983 on April 20, after a Greenspan Commission split the pain across workers, firms, and people already on the rolls. The Bipartisan Policy Center notes that the 1983 deal set the cap so that 90 percent of covered wages were taxed. Wage growth at the top has since pulled that share down to 83 percent of covered wages.
HOW THE 1983 DEAL SHARED THE BILL
- Payroll taxes: Scheduled rate increases were pulled forward, including a faster climb toward the 6.2 percent OASDI rate still in force.
- COLA delay: The July 1983 cost-of-living raise for people already on the rolls was pushed six months, to January 1984.
- Tax on benefits: Higher-income retirees began paying income tax on a share of their checks, with that money credited back to the trust funds.
- Retirement age: Full retirement age rose in steps from 65 to 67, a cut in lifetime benefits for later cohorts.
- Coverage: Newly hired federal workers were brought into the system, widening the tax base.
The worker-to-beneficiary math has moved in the same direction. The Bipartisan Policy Center puts the ratio at more than 5-to-1 in 1960, 2.9-to-1 in 2026, and 2.2-to-1 by the 2070s. Average benefits have also grown in real terms because initial checks are tied to national wages, which have outpaced prices. BPC cites a recent average retired-worker check of $2,017 a month.
What Happens to Benefits if Congress Lifts the Cap?
If lawmakers tax wages above $184,500 and also credit those wages in the benefit formula, high earners pay more and later collect more, so the trust fund keeps only part of the new cash. If they tax the extra wages and leave the benefit formula capped, the new money is a pure transfer from people above the line to everyone else. That second version raises more for solvency. It also turns a wage-insurance tax into something closer to an income-tax surcharge that happens to be labeled Social Security.
Sens. Bernie Moreno, R-Ohio, and Elizabeth Warren, D-Mass., made the fairness case in a June joint op-ed, pointing out that most Americans earn less than the cap and so pay on every dollar while top earners pay on a fraction. “Why should a middle-class nurse pay a larger share of her paycheck than a wealthy corporate lawyer?” they wrote. They proposed removing the cap and cited a Peter G. Peterson Foundation estimate of about $3 trillion over 10 years.
That 10-year cash figure is not the 75-year hole. It also does not land only on billionaires. The other 6.2 percent is the employer match, which hits law firms, hospitals, software shops, and any small business that pays a handful of salaries above the cap. Florida Gov. Ron DeSantis called the Moreno-Warren idea “a hammer blow to small businesses.” Grover Norquist, president of Americans for Tax Reform, branded it a more radical tax hike than Sen. Bernie Sanders or Kamala Harris had campaigned on.
Capital income sits outside the fight unless Congress writes it in. Dividends, capital gains, and carried interest are not FICA wages. Sen. Sheldon Whitehouse, D-R.I., and Rep. Brendan Boyle, D-Pa., would lift the payroll-tax threshold to $400,000 and also tax investment earnings, leaving a donut hole between the current cap and $400,000. Rep. John Larson, D-Conn., and Sen. Richard Blumenthal, D-Conn., took a harder line in the Social Security 2100 Act, which would repeal the wage-base limit after 2026, fold the extra earnings into the benefit formula, and add a 12.4 percent tax on some investment income above $400,000. Josh Turek, a Democratic Senate candidate in Iowa, has argued that wealthy filers “pay Social Security tax for the first few minutes of the year, but we have teachers… that are paying year-round.”
Scrapping the Cap Still Leaves a Solvency Hole
CRFB’s reading of the 2026 report is blunt: tools that would once have restored 75-year balance, including elimination of the $184,500 cap, would now close around half of the solvency gap. The rest still has to come from a higher tax rate, a tax on investment income, slower benefit growth, a later claiming age, or the automatic 22 percent cut. Sen. Chuck Grassley, R-Iowa, told a June 24 Finance subcommittee hearing that the gap “cannot realistically be plugged simply through tax hikes on the wealthy.”
OPTIONS ON THE TABLE, AND WHAT THEY LEAVE UNPAID
| Approach | Core move | What it does not do |
|---|---|---|
| Do nothing | Pay only incoming tax after late 2032 | Stop a 22 percent cut in OASI checks, growing to 38 percent by 2100 |
| Scrap or lift the wage cap | Apply 12.4 percent above $184,500 | Close the full 4.42 percent-of-payroll hole, especially if extra wages also raise extra benefits |
| Donut hole plus investment tax | Restart FICA above $400,000 and tax some capital income | Tax wages between the current cap and $400,000 until the hole closes |
| Cassidy-Kaine fund | Borrow $1.5 trillion for a 75-year stock fund | Avoid another $25.1 trillion in borrowing, $26.6 trillion in all |
| PROMISE Act process | Force a 50-year solvency plan onto the floor | Name the tax rates or benefit changes before the vote |
A one-point rise in the 12.4 percent rate would close roughly a quarter of the gap in CRFB’s public scoring of rate changes; two points would close about half. That is the same neighborhood as eliminating the cap, and it would fall on every covered worker and every employer, not only the 6 percent above the line. No one with a leadership microphone is advertising that trade.
Cassidy and Kaine Would Borrow $1.5 Trillion First
Sens. Bill Cassidy, R-La., and Tim Kaine, D-Va., have tried to skip both the tax fight and the benefit fight. Their plan would have the Treasury borrow $1.5 trillion over five years, park it in a separate fund of stocks and other risk assets for 75 years, and keep paying scheduled benefits by borrowing another $25.1 trillion in the meantime. Returns from the fund would then repay the Treasury and, in the senators’ telling, cover the $26.6 trillion pile.
Anqi Chen, Alicia H. Munnell, and Jean-Pierre Aubry at Boston College’s Center for Retirement Research ran simulations of a $1.5 trillion investment fund against that debt. Cassidy-Kaine assumes an 8.9 percent nominal return, about 6.5 percent real after the trustees’ 2.4 percent inflation assumption. Even at that rate, net assets do not cover the $26.6 trillion in most outcomes. At a 4.0 percent real return, closer to what several large asset managers are publishing, the success rate falls sharply. A further haircut for extra national debt makes it worse.
The Cassidy-Kaine proposal will most likely leave the government with a big pile of debt in the 75th year, requiring large interest payments. The more productive route is to restore solvency to Social Security first and then phase in equities.
Anqi Chen, Alicia H. Munnell, and Jean-Pierre Aubry, Center for Retirement Research at Boston College
Munnell had already called the plan a “flight of fancy.” CRFB, in a separate March analysis, warned that a sovereign debt fund cannot save Social Security and that the extra borrowing would pressure a bond market already carrying a heavy load. Equities can beat Treasurys over long stretches. They also slump, and this design asks the Treasury to finance both the bet and every year’s benefit gap until the bet is done.
The Lame-Duck Bill That Unites Opponents
The House comments from Cole and Smucker are the public-facing version of a tax-only repair. The bill actually moving in the Senate is a process vehicle. Retiring Sens. Dick Durbin, D-Ill., and Cassidy have gathered a group of eight centrists behind the PROMISE Act, which would charge the Social Security Advisory Board with writing a plan that keeps the trust funds solvent for 50 years and then force Congress to vote. Sponsors are aiming at the lame-duck session after the November 2026 elections, when several of them will already be on the way out.
That is why the opposition is wider than the usual left-right split. AARP wants benefit cuts taken off the table and wants any fix done in regular order. Nancy LeaMond, AARP’s chief advocacy and engagement officer, has said strengthening Social Security “should happen through regular order, in full public view, with openness and transparency.” Sanders wants Democrats to lift the payroll-tax cap instead. Norquist is lobbying Republican leaders against a bill he reads as a device to manufacture GOP votes for tax hikes. President Donald Trump has pledged to reject Social Security cuts, which boxes in any board plan that leans on slower benefit growth.
A board that must produce 50-year solvency cannot live on the wage cap alone, given CRFB’s finding that eliminating it now fills only around half the hole. The likely draft is a mix: more revenue, including some form of cap change, plus slower growth in future benefits or a later full retirement age. That is the 1983 shape, minus the emergency atmosphere of a fund weeks from missing checks. It is also the shape Cole’s own warning points toward. A tax-only conversation is easier to have on television. The remaining half of the 4.42 percent gap still has to be named, voted, and phased in before late 2032, or the cut arrives on its own.
Disclaimer: This article is news reporting and analysis of Social Security financing proposals and is for information only. It is not tax, investment, legal, or retirement-planning advice, and it does not recommend any bill, tax change, claiming age, or portfolio strategy. Readers who need advice on their own benefits, payroll taxes, or retirement income should consult a qualified tax professional, enrolled agent, or certified financial planner before acting. Figures and legislative statuses reflect the Social Security trustees, congressional proposals, and research cited as of the sources’ dates and may change with new reports or votes.

Amazon Pauses 21 Air and Keeps Its Cargo Fleet Flying

NATS Grounds Nearly 2,100 Flights After a Third Failure

Raising the Social Security Wage Cap Still Leaves a Hole

Beats Gets Apple’s iPhone Gamepad After Cases and Cables

Trump Backs Clarity Act Ethics Rules That Omit Children

Microsoft Prints Azure’s $29.42 Billion Quarter and Shrinks the Map

What is a Corpak Feeding Tube: A Comprehensive Guide

UltraTech’s Ultravolt Launch Puts Cable Multiples on Trial

IXI Autofocus Glasses Debut at CES 2026

Candere Names Smriti Mandhana Brand Ambassador Alongside Shah Rukh Khan
-
 NEWS4 weeks ago
Microsoft Prints Azure’s $29.42 Billion Quarter and Shrinks the Map
-
 BUSINESS4 weeks ago
UltraTech’s Ultravolt Launch Puts Cable Multiples on Trial
-
 LIFESTYLE3 years ago
What is a Corpak Feeding Tube: A Comprehensive Guide
-
 NEWS9 months ago
IXI Autofocus Glasses Debut at CES 2026
-
 BUSINESS3 months ago
Candere Names Smriti Mandhana Brand Ambassador Alongside Shah Rukh Khan
-
 NEWS3 years ago
audax: A New Digital Banking Technology Solution by SC Ventures
-
 LIFESTYLE3 years ago
What are the Most Inbred Countries?
-

 NEWS3 months ago
Atlanta’s Data Center Boom Is Running Into Its Water Supply